Hyperscaler Debt Binge Risks Curbing AI Access for Emerging Nations
The largest cloud companies in the world are borrowing money at a pace the technology industry has never seen before. They are doing it for one reason: artificial intelligence is expensive, and the bill is coming due faster than their own profits can cover it. But there is a side effect that almost nobody is talking about, and it could shape the next decade of AI more than any single model release. When hyperscalers flood global credit markets with debt, they compete for the same pool of money that emerging nations rely on to build their own infrastructure. As of late 2026, that competition is starting to bite.
This is not a story about one company's balance sheet. It is a story about who gets to build AI, who only gets to rent it, and what happens to the billions of people caught on the wrong side of that line.
The Cost of Building Intelligence
Training and running frontier AI models requires physical things. Data centers the size of small towns. Specialized chips that are hard to manufacture and even harder to buy in bulk. Power plants and transmission lines. Water for cooling. Fiber for moving enormous amounts of data between locations. None of that is cheap, and none of it arrives quickly.
For years, the hyperscalers funded their expansion out of cash flow. Cloud computing was a cash machine, and the profits paid for the next wave of servers. AI broke that model. The capital requirements jumped so dramatically that even the most profitable companies in tech could no longer self-fund their ambitions. So they turned to the bond market.
Investors have been happy to lend. Hyperscaler debt carries strong credit ratings, offers a yield, and comes attached to the most compelling growth narrative of the decade. For pension funds, insurers, and asset managers hunting for safe returns, these bonds look like a gift. The demand has been enormous, and the issuance has kept growing.
That is where the trouble begins.
When Big Borrowers Crowd Out Everyone Else
Global capital is not infinite. At any given moment, there is a finite pool of money looking for a home. When a handful of enormous, highly rated borrowers absorb a very large share of that pool, everyone else has to compete for what is left. Economists call this crowding out, and it is one of the oldest dynamics in finance.
Emerging market sovereigns are especially exposed. Their bonds already carry more risk, which means investors demand higher yields to hold them. When a safer, familiar alternative is available in huge supply, the calculus shifts. A fund manager who can buy hyperscaler paper backed by dominant cloud businesses may decide the extra yield from an emerging market sovereign is no longer worth the risk. Demand falls. Yields rise. Borrowing gets more expensive for countries that can least afford it.
The problem compounds because of currency. Many emerging nations borrow in foreign currency, so their debt burden is sensitive to exchange rates and global risk appetite. A world where capital is being pulled toward a handful of AI infrastructure projects in wealthy regions is a world where that appetite runs thinner for everyone else.
Why This Is an AI Story, Not Just a Finance Story
It is tempting to file this away as a markets topic. That would be a mistake. The cost of capital determines what gets built, and what gets built determines who can use AI.
An emerging nation that wants a real stake in the AI economy needs several things at once: reliable electricity, high-bandwidth connectivity, domestic or regional data centers, a workforce trained to build and deploy AI systems, and the ability to store and govern data under its own laws. Every one of those requires long-term financing. If that financing becomes more expensive, projects get delayed, scaled down, or cancelled outright.
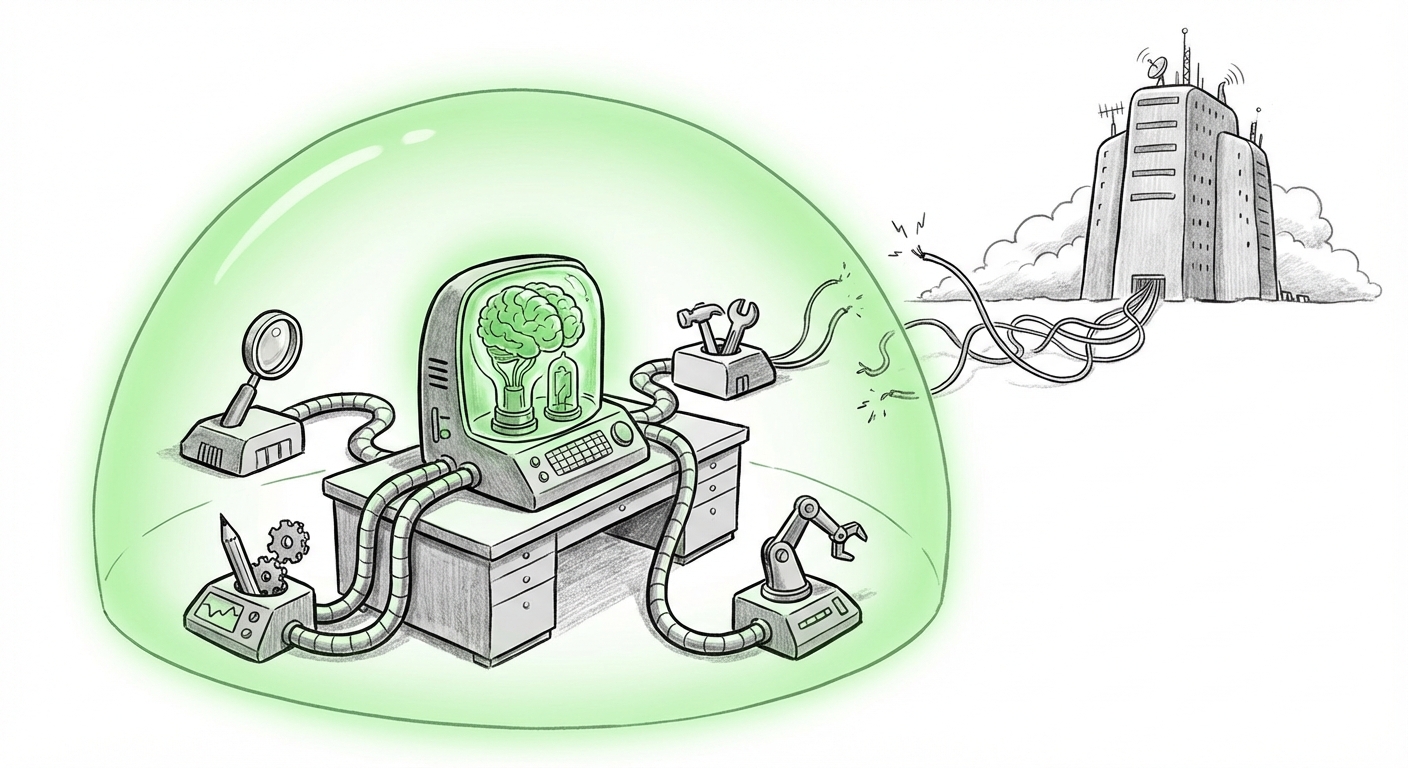
The alternative is dependency. Countries that cannot build their own compute become pure importers of intelligence produced elsewhere. They pay per token, per seat, per API call, and they accept the terms attached. Their data flows out. Their language coverage depends on whether a foreign model maker bothered to train on it. Their critical systems run on software they do not control and cannot inspect.
This is not a hypothetical. It is already the default state for much of the world, and rising capital costs make it harder to escape.
What This Means for the Future of AI
A Two-Speed AI World
The most likely outcome is a sharp split. A small number of regions will host the compute, own the models, and set the prices. Everyone else will consume. That split will not just be economic, it will shape which problems get solved first. AI research tends to follow the money, and the money is concentrated. Diseases, crops, languages, and climate challenges that matter most in lower-income regions will get less attention simply because fewer researchers are funded to work on them.
Concentration of Pricing Power
Whoever owns compute owns the toll booth. As debt-funded capacity comes online, the companies that built it need to service that debt. That creates strong pressure to keep prices healthy and utilization high. For businesses in emerging markets, the practical effect is that AI costs become a recurring foreign currency expense, one that behaves like an import bill rather than a domestic utility.
Less Model Diversity
Language and cultural context matter in AI. A model trained mostly on high-resource languages performs poorly on low-resource ones. The fewer places that can afford to train and fine-tune their own models, the more the global AI ecosystem converges on a narrow set of assumptions. That is a quality problem as much as a fairness problem.
Talent Moves Toward Capital
Researchers and engineers go where the compute is. When a country cannot offer cutting-edge infrastructure, its best people leave. That drain makes it even harder to build domestic capacity later, creating a loop that is hard to break.
Practical Implications for Businesses
For companies operating outside the wealthy compute hubs, the strategic response is not to wait for conditions to improve. It is to design around volatility.
- Assume AI costs will rise and swing. Treat AI spend like a foreign currency exposure. Budget for it, forecast it, and build flexibility into contracts.
- Design for model portability. Avoid deep lock-in to a single provider's proprietary tooling. Where it makes sense, keep the option to swap models as prices and availability change.
- Use smaller, efficient models where they work. Not every task needs a frontier model. Right-sized models running closer to the data can cut both cost and latency.
- Push inference to the edge. On-device processing reduces reliance on imported compute and keeps sensitive data local.
- Think in terms of regional partners. Consortiums, shared infrastructure deals, and cross-border data center projects can spread the capital burden across several countries.
What Governments and Institutions Should Watch
Policymakers have levers, but they need to use them early. The most important is energy. AI capacity follows cheap, reliable power, and countries that invest in generation and grid capacity now will be far better positioned than those that wait. Skills investment matters just as much, compute without trained people is a very expensive space heater.
Development finance and blended capital structures can help close the gap, but they need to move at the speed of the private market rather than the speed of a committee. Data governance frameworks, established before foreign AI providers become deeply embedded, give countries something to negotiate with. Without them, the terms are set elsewhere.
What to Watch Next
Several signals will reveal how this plays out. Watch the pace of hyperscaler debt issuance and whether credit spreads widen, a shift in investor enthusiasm would change the entire picture. Watch emerging market sovereign borrowing costs for signs of crowding out. Watch whether new data center announcements cluster even more tightly in a few regions. And watch for policy responses, because governments that feel locked out of the AI economy will start pushing back.
The deeper question is whether AI becomes a broadly distributed utility or a premium service sold from a handful of locations. Debt markets are quietly answering that question right now, one bond issue at a time.
The Bottom Line
The AI boom is being financed with borrowed money, and that borrowing has consequences far beyond the companies doing it. Capital that flows into hyperscaler bonds is capital that does not flow into emerging market infrastructure. The result is a world where AI capability concentrates, dependency deepens, and the countries with the most to gain from the technology have the hardest time affording it.
That is not inevitable, but it will not fix itself. Businesses should plan for higher, more volatile AI costs and build flexibility into their stacks. Governments should treat compute, power, and skills as strategic infrastructure. And the industry should be honest that the infrastructure race it is running is also a race to decide who gets to participate in what comes next.